 Bad Credit Loan Guide
How to Check and Correct Your UK Credit Report Before Applying
Why Your Credit File Matters Before You Apply
Lenders base borrowing decisions on your credit report, not just your score. A single outdated default or a fraudulent account listed in your name can push your application into an automatic decline, even when your actual financial behaviour has been sound for years. Reviewing your file before you apply gives you time to fix problems rather than discovering them mid-application.
UK lenders typically look at data held by Experian, Equifax, and TransUnion. Because each agency holds slightly different information from different creditors, your report can look materially different across all three. Checking all three before a loan application is not excessive caution; it is straightforward risk management.
How to Get Your Free Credit Reports
Every UK consumer is entitled to access their statutory credit report for free from each of the three main credit reference agencies: Experian, Equifax, and TransUnion. The statutory report is a full data export, not a summarised score, so request that specifically.
- Experian: Apply at experian.co.uk. The free statutory report is separate from the paid CreditExpert subscription.
- Equifax: Access via clearscore.com, which uses Equifax data and updates weekly at no charge.
- TransUnion: Available through creditkarma.co.uk or checkmyfile.com, the latter aggregating all three agencies in one view for a small monthly fee after a free trial period.
Download or save each report as a PDF once you have it. You will need a dated copy to reference if you raise a dispute later.
Understanding the Scoring Thresholds
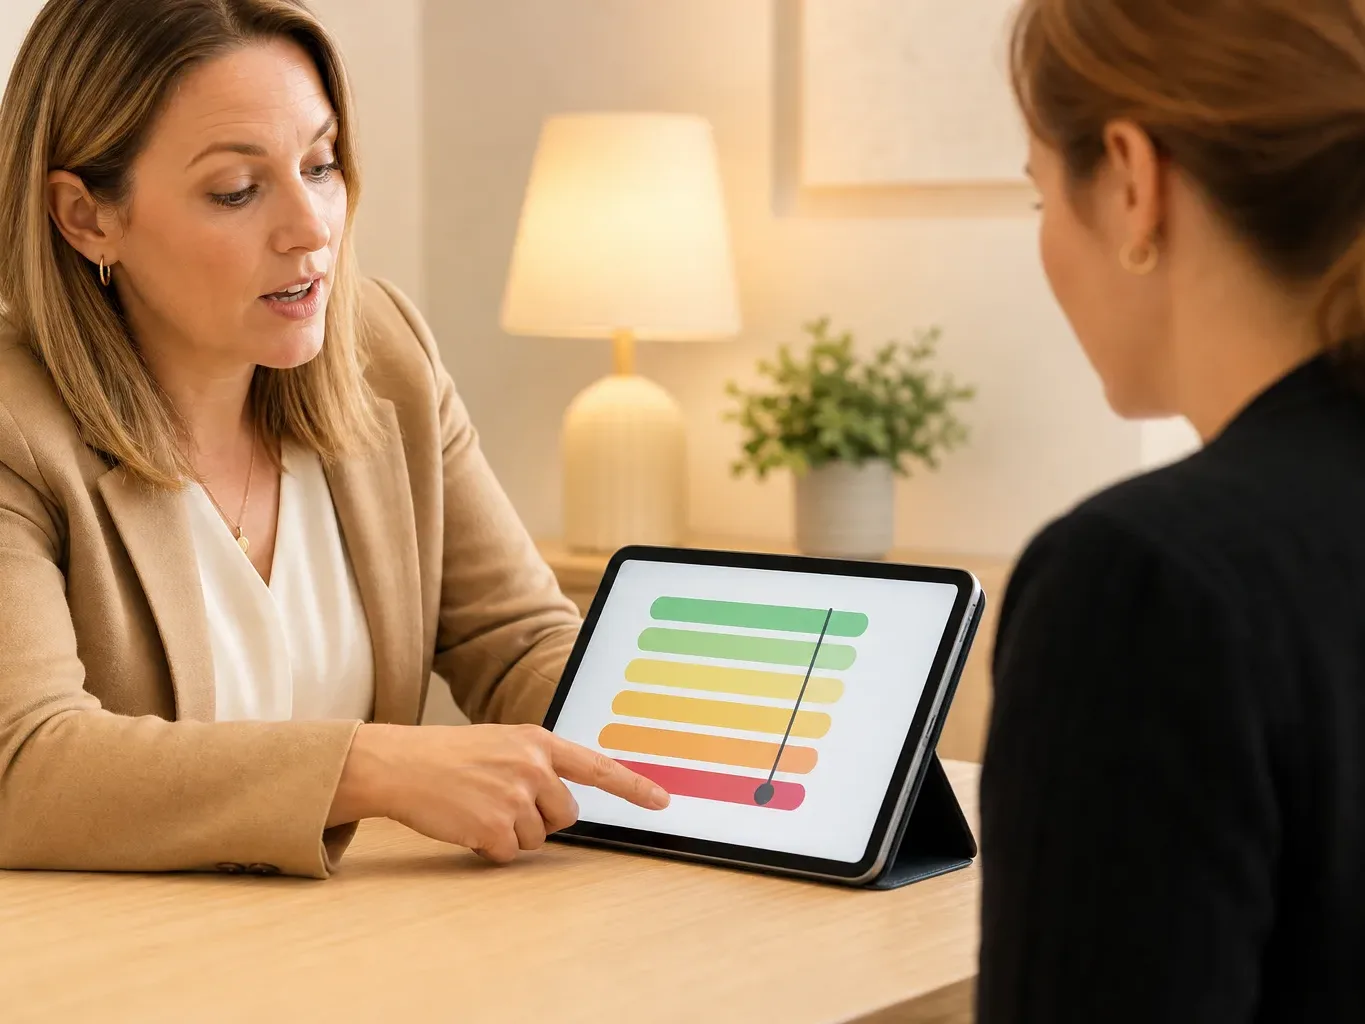
Each agency scores you on a different numerical scale, so a raw number means nothing without naming the source. On Experian's 0–999 scale, a score below 721 falls into the poor band. On Equifax's 0–700 scale, below 439 is classified as poor. TransUnion uses a 0–710 scale, and below 566 is considered poor.
These thresholds matter because bad-credit personal loans typically carry a representative APR of 29.9% to 99.9%, reflecting the higher risk lenders associate with scores in those lower bands. Improving your score even modestly before applying can move you into a better pricing tier with some lenders.
What to Look for When You Review Each Report
Work through each report section by section rather than scanning it quickly.
Personal Details
Check your full name, date of birth, and all linked addresses. An old address you no longer live at should still be on file if you had credit there, but a completely unfamiliar address is a red flag for identity fraud. Contact the agency immediately if you spot one.
Account Listings
Every credit account, including mobile phone contracts and Buy Now Pay Later arrangements, should appear accurately. Confirm the balance, credit limit, and payment history columns match your own records. A missed payment that you actually made on time is a correctable error. So is a settled account still showing an outstanding balance.
Linked Financial Associations
If you held a joint account with a former partner, their poor credit behaviour can affect your profile through what is called a financial association. You can apply to have that link removed once the shared account is fully closed.
Hard Search Footprints
A hard credit search is recorded on your credit file and can be seen by other lenders for up to 12 months. Multiple hard searches in a short window suggest credit-seeking behaviour and can lower your score. Identify any searches you did not authorise, as these may indicate a fraud attempt.
How to Dispute Errors
All three agencies offer a formal dispute process, and lenders are legally obliged to investigate a challenge within 28 days under the UK Consumer Credit Act.
Step 1 - Gather Your Evidence
Before contacting an agency, collect documentary proof. A bank statement showing a payment left your account on a specific date is stronger than a verbal recollection. Screenshots of online accounts, payment confirmation emails, and account closure letters all constitute useful evidence.
Step 2 - Raise the Dispute Directly
Each agency has an online dispute portal. Log in, locate the specific entry, and select the option to raise a query or correction request. Describe the error clearly, attach your evidence, and keep a record of the submission date and reference number. The agency contacts the lender on your behalf and must report back to you with the outcome.
Step 3 - Add a Notice of Correction
If a dispute is not resolved in your favour but you believe the entry is misleading, you can add a Notice of Correction. This is a short statement of up to 200 words that you write yourself, explaining the context behind an entry. Lenders are required to read it before making a decision. It does not remove the entry, but it gives you a voice in how the information is interpreted.
Step 4 - Escalate If Needed
If the agency or lender refuses to correct a genuine error, raise a formal complaint with the lender first. If they issue a final response you disagree with, you can refer the matter to the Financial Ombudsman Service. That referral must generally be made within 6 months of the lender's final response letter.
Practical Steps to Strengthen Your File Before Applying
Beyond correcting errors, there are concrete actions that improve how your report reads to a lender within a relatively short timeframe.
Register on the electoral roll at your current address if you have not already. Lenders use it to verify your identity, and its absence genuinely reduces approval odds. Pay down any revolving credit balances to below 30% of their limit, since high utilisation signals financial stress even when payments are on time.
Use a soft search eligibility checker before submitting any formal loan application. A soft search eligibility check does not affect your credit score and is not visible to other lenders, so you can compare indicative offers without leaving a footprint. This matters especially when you are rebuilding your file and cannot afford unnecessary hard searches.
Space out any new credit applications by at least three months where possible. If you are applying for a bad-credit personal loan in the typical range of £100 to £5,000, lenders expect some credit history imperfection; what they are also watching is whether you are applying everywhere at once. A clean, well-maintained file with accurate information and a sensible recent search history is a credible one, and that is the goal before you submit.
Frequently Asked Questions
How Can I Get Free Credit Reports from All Three Bureaus?
Every UK consumer is entitled to their statutory credit report for free from Experian, Equifax, and TransUnion. Request directly from Experian at experian.co.uk, access Equifax data through ClearScore, and TransUnion data through Credit Karma or checkmyfile.com. The statutory report is a full data file, not just a summary score.
Why Do Lenders Look at Credit Reports?
Lenders use credit reports to assess how reliably you have managed debt in the past. The report shows open and closed accounts, payment history, outstanding balances, and any defaults or county court judgements. This information helps lenders decide whether to approve an application and at what interest rate, with higher-risk profiles typically attracting a higher representative APR.
How Can I Check My Credit Score?
You can check your credit score for free through ClearScore (Equifax data), Credit Karma (TransUnion data), or Experian's free account. For a combined view across all three agencies, checkmyfile.com offers a multi-agency report. Remember that each agency uses a different scale, so always name the agency alongside any score you are quoting.
What's the Most Accurate Way to Check Credit Score?
No single score is definitively the most accurate because UK lenders do not all use the same agency or scoring model. Checking your report from all three agencies, Experian, Equifax, and TransUnion, gives the most complete picture. Some lenders use proprietary scoring models, so focusing on the accuracy of the underlying data in your report is more useful than chasing a particular score number.
Is 500 a Poor Credit Score?
Whether 500 is a poor score depends entirely on which credit reference agency produced it. On Experian's 0–999 scale, 500 falls in the poor band since poor is defined as below 721. On Equifax's 0–700 scale, 500 sits in the fair range because poor is below 439. On TransUnion's 0–710 scale, 500 falls just below the poor threshold of 566. Always check which agency's scale you are reading before drawing conclusions.